Talk to us

TechTalk: Estate planning just became a tech job too

By
Amy North

Technology

Estate planning has always been a blend of tax rules, family dynamics and adviser judgement. It is one of those areas where advisers often say, “it depends”, because the picture can shift quickly. This year, it feels like the picture is shifting faster than ever.

Upcoming changes to pensions, BR and APR reliefs, rule caps, and the impact of compounding on client estates over time are creating a new kind of challenge. Complexity is rising, planning windows are narrowing, and advisers are being asked bigger questions about intergenerational wealth.

The silver lining is that tech in our space is finally catching up. Tools that would have seemed ambitious not long ago can now model what really matters for clients, including long term estate projections and rule based triggers.

This month, I want to spotlight two things. First, the launch of a new IHT calculator created by TIME Investments. Second, a quick roundup of the latest adviser tech updates that caught our eye.

Let’s get into it.


A new IHT calculator that brings clarity to the chaos

TIME Investments have released a new IHT calculator that several of you have already asked about. You can try it here:

Inheritance Tax Calculator

It takes a client’s current estate and projects their future IHT position year by year up to 2040. It also builds in the upcoming rule changes across BR, APR and pensions. For advisers working with clients who are unsure how these moving parts interact, this kind of forward view can be invaluable.

Here are the client situations where this tool becomes particularly helpful:

  • Clients with AIM BR investments, where BR drops to 50 percent in April 2026.
  • Clients considering AIM BR for the first time. Even reduced relief can still drive meaningful impact.
  • Households with TIME Advance or similar BR solutions, particularly where more than one million of BR may be invested.
  • Clients relying on pension assets as part of estate planning, because pensions will start to be included in the estate from April 2027.
  • Business or farm owners facing BR and APR relief caps from April 2026.
  • Property heavy clients where house value growth drives long term IHT exposure.
  • Blended estates involving pensions, BR assets, AIM shares, investments and cash.
  • Families delaying decisions and needing a clear view of the cost of waiting.

For advisers, it has five practical benefits.

  1. It simplifies complexity.
  2. It saves time by producing a clean, downloadable client report.
  3. It boosts client engagement in estate planning conversations.
  4. It highlights planning opportunities at the right time.
  5. It supports compliance with a transparent advice record.

With IHT receipts now at a record high of £7.5 billion, anything that helps clients understand their future position without overwhelming them is a welcome addition to the toolkit.


A quick look at what else is happening in adviser tech

The last month has been busy. Several providers have released updates worth keeping on your radar.


Quilter’s WealthSelect on Transact

This update strengthens the available MPS options on Transact and may help streamline discussions for advisers who want platform consistency without sacrificing choice.


ebi launches a fund of funds range

This addition will appeal to firms looking for simplified portfolio structures that still feel evidence based. Source:

ebi Portfolios launches Fund of Funds range


Dynamic Planner achieves an industry first

Dynamic Planner has earned AI certification, something that will reassure firms who want to use AI guided tools in a compliant, transparent way. Source:

Dynamic Planner achieves industry first AI certification


AdviserSoftware’s new comparison tool

This tool allows advisers to compare AI solutions with more clarity, something many firms have asked for as the market gets crowded. Source:

AdviserSoftware.com launches AI comparison tool for advisers


AJ Bell’s suite of adviser tools

AJ Bell has expanded its adviser toolkit, giving more options for cash flow, modelling and portfolio planning tasks. Source:

AJ Bell unveils suite of adviser tools


These updates point to a trend I think we will see more of. Adviser tech is no longer just about creating efficiencies, it is becoming a way to understand complexity and explain it simply.

That is exactly what clients value.


Looking ahead

The more rules shift, the more advisers will lean on tools that bring clarity without adding noise. What matters is not high tech for the sake of it, but tech that helps clients make informed decisions with confidence.

If this resonates with what you are seeing, I would love to hear from you.
 

Why “intelligible pensions” is the tech question of our time

Ask any adviser or paraplanner what’s hardest to explain, and pensions will be near the top of the list. Between legacy schemes, tax quirks, retirement choices and regulation, even a “plain English” summary can sound like a puzzle.

So when I saw the headline “Could AI be the answer to making pensions intelligible for all?”– I stopped scrolling. Because if there’s one part of advice crying out for clarity, it’s pensions.

This month’s TechTalk takes that question and pairs it with three big tech moves in our sector – to explore how AI might finally help advice make senseto everyone.


1 | “Intelligible” isn’t simple – it’s structural

A recent Professional Adviser article hit the nail on the head: pension language isn’t confusing by accident. It’s confusing because the system itself is complex. AI can’t magic that away – but it canact as a translator between the system and the saver.

In practice, that could mean:

  • Explaining scheme rules or benefits in plain, personal terms
  • Letting users ask questions in their own words (and get answers that build confidence)
  • Tailoring explanations to different literacy or knowledge levels
  • Spotting when someone’s lost, and suggesting when to bring a human into the loop

We’re already seeing early versions of this – “pension specialist” chatbots that can interpret scheme documents and respond conversationally. It’s promising, but as always, the line between simplification and distortion is thin. Accuracy, oversight, and context are everything.


2 | AI is moving from experiment to infrastructure

If you look at what’s happening across financial services, the pattern is clear – AI isn’t just a novelty anymore. It’s being built into the backbone of how firms work.

  • Legal & General × Microsoft are using AI to enhance client interactions and anticipate needs.
  • AJ Bell + Dynamic Planner have integrated to remove manual handoffs – the groundwork AI depends on.
  • Nucleus / Third Financial + Titan Wealth are taking it further with platform-as-a-service flexibility, giving firms room to plug in AI tools of their own.

The message? These aren’t pilot projects anymore. They’re early signs of AI becoming part of the advice architecture– less about shiny new tools, more about smoother, smarter systems.


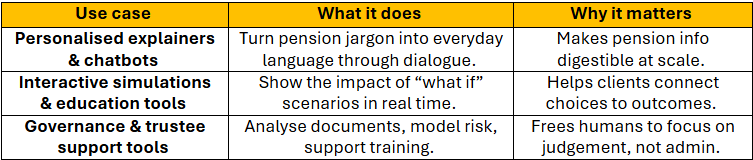
3 | Where AI is already proving useful

A few real-world examples show where AI is already earning its place:

But let’s not gloss over the caveats – hallucinations, data privacy, and regulatory limits still need careful handling. Used well, AI could raise standards. Used badly, it risks confusion at scale.


4 | Four questions to ask before you jump in

If you’re thinking about introducing AI to improve clarity, start by asking:

1️⃣ Where are clients getting stuck? Is it in benefit summaries, decumulation options, or tax explanations? Start where misunderstanding costs the most time.

2️⃣ Do your systems talk to each other? AI is only as smart as the data it can reach. If your tools aren’t connected, your AI will be guessing in the dark.

3️⃣ What’s your “human handover” rule? Decide early when a person should step in – and make sure that’s logged, not left to chance.

4️⃣ How will you measure understanding? Track feedback, rewording requests, and drop-off points. They’re gold dust for continuous improvement.

AI should assistadvice, not automate it. The moment clients feel “talked at” instead of “spoken with,” we’ve missed the point.


5 | The regulatory line is still forming

Right now, there’s a healthy debate about whether AI explanations could ever count as “advice.” The FCA’s watching closely – especially as the 2026 pensions dashboards start taking shape.

Experts are already urging boards to build AI governance policies: define your scope, set guardrails, and make sure accountability stays human. The PLSAhas echoed that message – cautious optimism, yes, but oversight must stay front and centre.


Final thoughts: yes – but only if we build it well

So, could AI make pensions intelligible for all? Yes – if we let it translate, not replace.

AI won’t remove complexity, but it can help bridge the gap between technical language and human understanding. Done right, it can make advice land– turning jargon into clarity, curiosity into confidence.

The real test isn’t whether AI can talk. It’s whether clients trust what it says.

If that’s the challenge your firm’s exploring, we’d love to hear how you’re approaching it – no pitch, just a shared curiosity about doing advice better.


Big names in adviser tech are making headlines again. Aberdeen, Intelliflo and ZeroKey recently announced a new partnership, aimed at streamlining adviser technology and tackling inefficiencies across the sector (Money Marketing). Add to that the Carlyle Group’s acquisition of Intelliflo (Carlyle release), and it feels like adviser tech is consolidating faster than some advice firms.

But behind the M&A noise, one theme keeps coming up in our conversations with advisers and paraplanners: data openness. Because the reality is that slick partnerships mean very little if the data still doesn’t flow properly.


Why advisers are frustrated with data

According to NextWealth’s Data Openness report, most advisers see inconsistent and poorly structured data as one of their biggest operational headaches. Platforms and providers all have their own formats, delivery methods, and quirks. For smaller firms it’s annoying. For consolidators it’s a nightmare.

Here’s what we’re hearing:

  • Data doesn’t flow cleanly between CRMs, platforms and back-office systems.
  • Transfers drag on because information is incomplete or locked in PDFs. (Platforms Association)
  • Advisers spend hours rekeying – which means less time with clients, and more chance of errors.

One consolidator quoted in the research summed it up bluntly: “Clients would be horrified if they knew what a shambles it is from different providers.”


The drivers for change

So why might this finally shift? Four main forces are pushing providers to get serious about data quality and accessibility:

  1. Regulation & Consumer Duty – The FCA expects firms to prove ongoing suitability, not just tick boxes once a year. You can’t do that without reliable, consistent data.
  2. Client expectations – Life doesn’t happen on an annual review cycle. Clients want real-time updates, not a paper pack once a year.
  3. Private equity ownership – With investors like Carlyle putting significant capital behind platforms, the pressure is on to show scalable, data-driven infrastructure.
  4. AI – Whether it’s report drafting, admin automation, or client portals, AI is only as good as the data it ingests. Garbage in, garbage out.


Where the innovation is happening

Across the market, we’re seeing a wave of new solutions designed to cut down on wasted admin and smooth advice workflows.

  • AI-driven Letters of Authority tools are reducing the chaos of provider packs, extracting structured data and cutting turnaround times.
  • Client portals are giving households access to valuations, tools and resources in real time – but only if the underlying data is clean.
  • AI meeting assistants are helping capture, transcribe and summarise client conversations, turning them into ready-to-use notes and draft suitability reports.

The common thread? All of them depend on clean, structured, open data.

No matter how smart the AI, if it’s working with half-finished fact-finds, locked PDFs, and missing product histories, it can’t deliver the outcomes advisers and clients expect.


Practical steps for advice firms

If you’re sitting in an ops or compliance seat at an advice firm, here are some practical questions to put on your agenda:

  • Ask your platforms: What data standards do you support? Can you provide structured feeds rather than PDFs?
  • Challenge delays: If transfer times are holding back client outcomes, escalate it. The Platforms Association is already putting pressure on providers – firms adding their voice will speed things up.
  • Audit your own systems: Are your back-office and CRM actually set up to receive and store structured data? Or are you still relying on manual workarounds?
  • Think beyond today: If you’re experimenting with AI (drafting reports, summarising calls, or using portals), remember: the investment only pays off if the underlying data is trustworthy.


Why this matters for advice culture

This isn’t just about efficiency. It’s about trust.

We’ve argued in our Advice Integrity white papers that retrospective file checking is a broken model. Real-time, evidenced advice is the only way to satisfy the FCA, reassure insurers, and build public confidence. Data openness is the bedrock of that shift.

If advisers can’t rely on their data, they can’t prove their advice integrity. And if clients can’t get clear, consistent information, they won’t trust the advice profession to deliver.


The takeaway

Tech partnerships, private equity deals, and shiny AI demos will keep making headlines. But the firms that win in the next five years will be the ones that get their data house in order – demanding openness from providers, aligning systems internally, and using that foundation to power real-time suitability and client confidence.

If this resonates with what you’re seeing in your own firm, we’d love to hear from you.


There’s a quiet but important shift happening across adviser tech, and if you blink, you might miss it. We’re not talking about a shiny new CRM or another data dashboard. We’re talking about what’s going on under the hood: integrations, partnerships, and AI pipelines that are shaping how advice gets built and delivered.

This month alone, we’ve seen:

  • FNZ team up with Microsoft to explore AI-powered advice tooling
  • Twenty7tec roll out a planning module with new CRM and cashflow integrations
  • City AM select Third Financial as a new platform partner

That’s three signals in one month pointing to a bigger trend: the advice tech stack is maturing, and integrations are becoming non-negotiable. But what does that really mean for financial planners and paraplanners? And where does it leave firms trying to deliver good advice, not just good systems?

Let’s dig in.

From Tools to Ecosystems

We’ve all worked with ‘tech’ that made life harder, not easier. A platform login that doesn’t speak to the CRM. A client risk score stuck in a PDF. Rekeying data into suitability reports (again). It’s no surprise that some advice firms have been slow to adopt new tools—they’ve been burned before.

But the nature of tech is changing. What we’re seeing now isn’t just more tools, but better connectivity between them.

Take the Twenty7tec update as a prime example. Their new integration layer links to iPipeline, Genovo, Timeline, and more, bridging the gap between planning, risk, and suitability workflows. According to CEO James Tucker, “the focus is now on connecting, not just creating”.

This shift matters. Because disconnected tools don’t just slow teams down—they create advice risk. When data gets re-entered or misaligned between systems, the integrity of the advice narrative suffers. And under Consumer Duty, ‘close enough’ just isn’t enough.


Enter AI: Assistant or Risk?

Then there’s AI. The FNZ–Microsoft announcement highlights a growing appetite to embed large language models (LLMs) into advice tooling—think summarisation, pattern detection, and even recommendation support.

On paper, this sounds great. But here’s the catch: if AI is reading client files, assessing risk, or suggesting actions, the need for human oversight skyrockets.

As we often say: AI can enhance, but not excuse. You still need a clear, defensible logic path. You still need to evidence why a recommendation was made, not just what the tool produced. And unless that AI is aligned to current FCA rulesets, it’s not a shortcut—it’s a liability.

For now, AI is best seen as a co-pilot. A speed enhancer. A second set of eyes. But the judgment? That still sits squarely with the adviser, and ideally, a structured suitability consultant process.


What Firms Can Do Right Now

If you’re reviewing your own tech stack or planning for 2026, here are three practical questions to ask:

  1. Are your systems talking to each other? Look at the points of friction: duplicate data entry, non-integrated risk tools, or manual report generation. These are not just time drains—they’re risk triggers.
  2. Do your tools support your people? If automation is creating more rework or generating documents that need constant editing, it’s not really helping. The best tools simplify, not complicate.
  3. Is your process auditable, not just operational? This is the big one. Under SYSC, COBS and Consumer Duty, you need more than a ‘completed’ advice file—you need to show the logic behind it, version it, and evidence that it aligns with client objectives and risk appetite.

If your QA team is still working at the end of the process, rather than alongside it, your tech is probably observational, not preventative.


Final Thought: It’s Not About the Tech. It’s About the Structure

At We Complement, we’re excited about tools like AMS (Advice Matrix Scoring), ARC (Advice Readiness Checks), and ASL (Advice Suitability Logic). But the point isn’t that we’ve got tech. It’s that we’ve built structure.

Every integration, every automation, every dashboard should serve a bigger purpose: helping firms deliver clearer, safer, and more consistent advice. If your tools aren’t doing that, it might be time for a rethink.

If any of this resonates with what you’re seeing in your firm, we’d love to hear from you. Whether you’re reviewing your tech stack, exploring AI, or just trying to smooth out your workflows, we’re always happy to chat. No pitch, just people who get it.


Speed. Integration. Capacity. It’s what every advice firm is chasing – but most platforms still make you jump through hoops. This month, we spotlight the tech making real strides in reducing admin, unlocking capacity, and getting clients over the line faster.

Here’s what’s hot this July 👇


Transact x Plannr: Faster Onboarding, Finally

If onboarding feels like death by paperwork, this update might be your moment of relief. Transact and Plannr Technologies Limited have teamed up to deliver an integration that automates client setup and dramatically reduces time to submission.

What’s in it: • Pre-population of Transact app forms via Plannr CRM • Seamless digital consent and ID verification • Straight-through processing (finally!)

💭 What this means for you: Think fewer manual touchpoints and faster turnaround for new business. If your team is still toggling between CRM, platform, and email trails just to open one account, it’s time to rethink your onboarding tech.

🔗 Read the full Transact + Plannr update


AdviserSoftware’s New AI Guide: One to Bookmark

There’s no shortage of AI noise – but this guide is worth your time. AdviserSoftware.com has launched a monthly AI-focused feature to help firms cut through the hype and understand where AI genuinely fits into their advice process.

💭 What this means for you: Whether you’re dabbling with AI for factfinding or client comms – or still figuring out what’s hype and what’s helpful – this guide can be your shortcut to clarity.

🔗 Check out the first edition


Facing a Capacity Crunch? Tech Might Be Your Exit Route

A standout piece from Professional Adviser highlights how advice firms are responding to rising demand and limited internal capacity – and yes, smart tech is the common thread.

From client triage tools to simplified workflows, the shift is clear: capacity isn’t just about hiring more people. It’s about making the people you already have more effective.

What this means for you: Think less about headcount and more about headspace. What’s eating up your team’s time – and is there tech to take it off their plate?

🔗 Read the full article


Final Thought: Smart Tech Isn’t Optional – It’s Strategic

If your tech doesn’t reduce friction, it’s not doing its job. Advisers don’t need “innovation.” They need: • Less rekeying • Faster onboarding • Cleaner compliance trails • Tools that earn back hours – not cost them

At We Complement, we work with firms who want exactly that. Tech that works for advisers, not the other way around.

📬 hello@wecomplement.co.uk 💬 Or drop us a message right here – we’re always up for a conversation about smarter operations.


The fintech landscape isn’t slowing down, and neither are the pressures on financial advice businesses. This month’s edition of TechTalk brings you the latest tech and regulatory developments—and more importantly, what they actually mean for your firm’s operations, compliance, and client experience.

Let’s dive in.

📊 Aviva & FNZ Launch New Tools for Advisers

Aviva for Advisers and FNZ have launched two new tools designed to help advisers work smarter, not harder:

  • Adviser Analytics Hub: a new MI suite inside Aviva’s Adviser Hub, offering data insights on client behaviour, segmentation, and business trends.
  • New asset transfer workflow – designed to simplify and speed up bulk client transfers onto the Aviva platform, with far less back-and-forth.

This goes beyond ‘more dashboards’—it’s a genuine push to align platform functionality with adviser realities.

💭 What this means for you: If your firm regularly battles with fragmented data or slow re-registration workflows, this tech could significantly reduce turnaround times and resource drain. If you’re platform-agnostic, now’s the time to review which providers are genuinely investing in adviser usability.

🔗 Explore Aviva & FNZ’s collaboration


🔐 Moneyinfo x ZeroKey: Integrated Client Data, Less Hassle

moneyinfo and ZeroKey have announced a new partnership that’s all about speeding up access to client data—without compromising quality.

The integration means advisers can:

  • Pull in data from providers, platforms, and open banking feeds
  • Pre-populate client profiles with minimal manual entry
  • Manage onboarding and reviews via a slick branded mobile app

It’s a tangible step forward in the drive toward smarter, faster client servicing.

💭 What this means for you: Ask your team how many minutes they spend hunting for accurate data before each review meeting. Now multiply that across your entire client base. This kind of automation doesn’t just cut cost—it unlocks capacity and reduces friction in your client journey.

🔗 See what Moneyinfo and ZeroKey are building


🧠 FCA & ICO: AI Is Inevitable—But You Need to Be Ready

In a joint update, the FCA and ICO made it clear: they support the use of AI in financial services—but they’re keeping a close eye on it.

Key points:

  • 85% of firms are already using or planning to use AI.
  • Data protection is a top barrier.
  • A new statutory AI code of practice is being developed to provide clearer guardrails.

The message is: innovation is encouraged, but it must be responsible, transparent, and client-focused.

💭 What this means for you: Whether you’re already using AI tools (e.g. for meeting notes, workflows, or MI) or just considering them, now is the time to audit your processes. Are your providers transparent about how data is handled? Are you confident you could demonstrate compliance?

🔗 Read the full FCA-ICO update


🛡️ Fraud Is Up—Here’s What That Means for Wealth Firms

A recent report shows a 73% increase in online fraud impacting UK businesses. For advice firms handling sensitive financial data, the implications are real and growing.

Advisers need to be aware that:

  • Cybercriminals are targeting firms with weak integrations and outdated client portals.
  • Trust can be eroded fast if clients feel their data isn’t secure.
  • Regulators are paying attention to how firms handle identity verification, document transfers, and platform access.

💭 What this means for you: Security is no longer just an IT issue—it’s a brand issue. Clients are asking more questions about where their data goes and how it’s protected. If your tech partners aren’t visibly proactive on security, it may be time to revisit the stack.


📈 FCA’s 2025–2030 Plan: Get Ready for Open Finance

The FCA’s new 5-year strategy reveals a vision where technology and trust go hand-in-hand. Open Finance is no longer a buzzword—it’s a roadmap.

Key highlights:

  • Laying the groundwork for Open Finance regulation and interoperability.
  • Supporting firms to adopt AI and digital tools safely.
  • Stronger focus on consumer outcomes through transparent data use.

💭 What this means for you: Open Finance could fundamentally reshape how you access, use, and share client data. Are your systems agile enough to keep up? The firms that invest in flexible, future-ready infrastructure today will be the ones that thrive when the frameworks land.


💬 Final Thought: Let’s Be Honest—The Tech Isn’t Slowing Down

The pace of change can be exhausting. But the firms that succeed aren’t the ones doing everything—they’re the ones doing the right things, at the right time.

This month’s updates are a reminder that:

  • Data must be trusted, not just available
  • AI must be usable and accountable
  • Client experience still trumps ‘shiny tech’

At We Complement, we help financial planning firms find their balance—making smart tech decisions that genuinely support advisers, paraplanners, and clients. If you’d like a sounding board on what to prioritise, we’re here.

📬 hello@wecomplement.co.uk 💬 Or just reply here—we always love hearing from planners who want to make tech work.


🔁 Follow us for more monthly TechTalk updates — no jargon, just insights that matter.


Practical Tech Insights for Paraplanners & Advisers

Welcome to the May edition of TechTalk! This month, we’re diving into the latest tech developments in financial services, with a focus on tools and innovations that can make your day-to-day work more efficient and client-focused.

🧠 Enhancing Client Understanding with Psychometric Tools

Scottish Widows has integrated a psychometric testing tool into their platform, developed in collaboration with Oxford Risk. This tool assesses clients’ risk attitudes, knowledge, and composure, providing deeper insights into their financial behaviours.

Why it matters:

  • For paraplanners: Gain richer client profiling data during onboarding.
  • For advisers: Tailor investment strategies that align more closely with client behaviours, potentially reducing reactive decision-making during market volatility.

👉 Learn more about the integration


🔧 Streamlining Platform Operations: The Platforms Association

A new body, the Platforms Association, has been established to address common challenges in the investment platform sector, such as re-registration delays and inconsistent tech interfaces. Members include major players like Aegon, Quilter, and Fidelity.

Why it matters:

  • For paraplanners and advisers: Expect improved platform interoperability and service standards, leading to more efficient client onboarding and management.

👉 Read about the Platforms Association’s goals


📊 Advancing Pension Visibility: Origo’s Dashboard Connection

Origo has successfully connected to the UK’s pensions dashboards ecosystem, a significant step towards providing clients with a consolidated view of their pension pots.Why it matters:

  • For paraplanners: Simplifies the fact-finding process by aggregating pension information.
  • For advisers: Enhances the ability to present comprehensive retirement planning strategies.

👉 Discover Origo’s role in the pensions dashboard


📑 Standardising Data Requests: The LoA Data Checklist

The LoA Data Checklist, developed by the Fix LoA Action Group (FLAG) and maintained by Criterion, is gaining traction with over 70 firms adopting it. This standard aims to streamline the process of obtaining information through Letters of Authority.

Why it matters:

  • For paraplanners and advisers: Reduces administrative burden by clarifying the data expected from providers, leading to faster and more accurate information retrieval.

👉 Explore the LoA Data Checklist


💰 Meeting Client Demand: AJ Bell’s Gilt MPS Launch

AJ Bell has introduced a new Gilt Model Portfolio Service (MPS), offering a low-cost investment option amid growing adviser demand for gilts. The service features a management charge of just 0.10% per annum and is available with a minimum investment of £10,000.

  • For advisers: Provides a tax-efficient, low-risk investment option suitable for clients seeking stable returns.

👉 Learn about AJ Bell’s Gilt MPS


🔍 Final Thoughts

The financial services world is evolving fast, and it’s clear that tech is no longer a ‘nice to have’—it’s central to how paraplanners and advisers deliver value, stay efficient, and serve clients better. From smarter client profiling to platform improvements and clearer data standards, these developments are all about making your day-to-day work easier and more effective.

At We Complement, we specialise in supporting financial planning businesses behind the scenes—whether that’s paraplanning, streamlining operations, or helping you adopt the right tech tools without the overwhelm. If you’re curious about how we can help, pop us a DM here on LinkedIn or drop us an email at hello@wecomplement.co.uk. We’re always up for a chat.


ISO/IEC 27001:2022 certified
UKAS-accredited information security management system
You can verify the validity of our ISO certificate via the UKAS register.

ISO/IEC 27001:2022 certified

Affiliate of

Consumer Duty Alliance

Proud to work with

Paradigm ValidPath

Contact

Old Brewery Business Centre
Castle Eden
Co. Durham
TS27 4SU

Tel: +44 (0)1472 728 030
Email: hello@wecomplement.co.uk

© 2026 We Complement | Privacy Policy
We Complement Limited registered in England & Wales under company number 13689379, ICO number ZB427271. Registered address: Old Brewery Business Centre, Castle Eden, Co. Durham, TS27 4SU.